Can Centene Sustain Its Turnaround Amid Membership Pressure?
Centene Corporation CNC is showing tangible signs of a profitability recovery, with second-quarter 2026 results reflecting better medical cost trends and stronger execution. Premium and service revenues increased 4.5% year over year, while adjusted EPS rose to $2.51 from a loss of 16 cents a year ago. CNC reaffirmed its 2026 adjusted EPS guidance floor to above $4.80. Its consolidated health benefits ratio improved to 89.6% from 93% a year ago.
Marketplace profitability has supported the recovery. Centene expects the business to generate a 4.5%-5% pretax margin in 2026, helped by better risk adjustment and moderating medical costs. Medicare is also progressing, with the PDP business expected to deliver a pretax margin above 3% and Medicare Advantage moving closer to breakeven.
Membership remains the main pressure point. Medicaid enrollment ended the second quarter of 2026 at 12.1 million, down 5.5% year over year, while Marketplace membership stood at roughly 3.5 million. Centene expects further attrition as eligibility reviews continue, with full-year Medicaid membership projected to decline 8%-9% from year-end 2025.
Improving Medicaid rates could cushion some of the impact. CNC raised its expected 2026 Medicaid rate increase to about 5%, while medical-cost trends remain in the mid-4% range. Continued progress in behavioral health, payment integrity and affordability initiatives could also support gradual margin recovery.
Centene is simultaneously simplifying its operating model and expanding technology and AI use to reduce costs. These efforts, combined with stronger Marketplace and Medicare profitability, provide a foundation for further recovery, though sustained improvement will depend on managing membership losses.
How Are Competitors Faring?
Some of CNC’s major competitors in the healthcare service provider space are UnitedHealth Group IncorporatedUNH and Humana Inc.HUM.
UnitedHealth is navigating similar membership and medical-cost pressures, particularly in Medicare Advantage and Medicaid. Still, its diversified Optum operations and cost-management efforts are supporting recovery. UNH raised its 2026 adjusted EPS outlook to $19.50-$20 following second-quarter results.
Humana is seeing strong Medicare Advantage membership growth while working to improve the profitability of its expanded member base. HUM’s CenterWell is adding another growth driver, with senior primary care patients up 27% through June 2026, supporting broader earnings diversification.
Centene’s Price Performance, Valuation & Estimates
Shares of CNC have surged 60.4% in the year-to-date period compared with the industry’s growth of 17.8%.
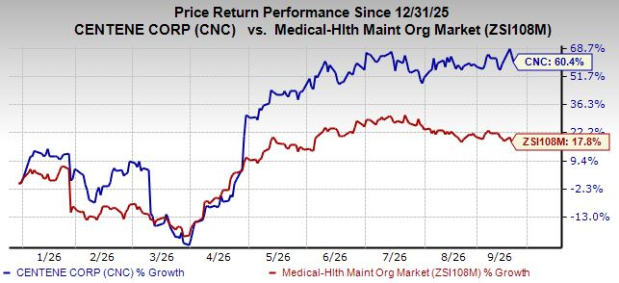
Image Source: Zacks Investment Research
From a valuation standpoint, Centene trades at a forward price-to-earnings ratio of 12.67, below the industry average of 15.44. CNC carries a Value Score of A.
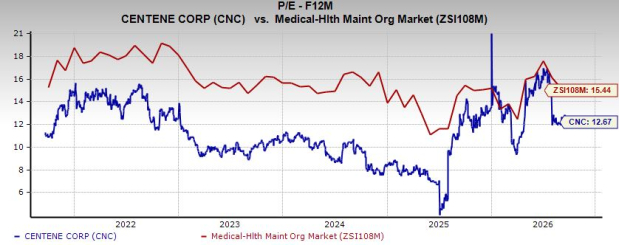
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Centene’s 2026 earnings is pegged at $4.89 per share, implying 135.1% growth from the year-ago period.
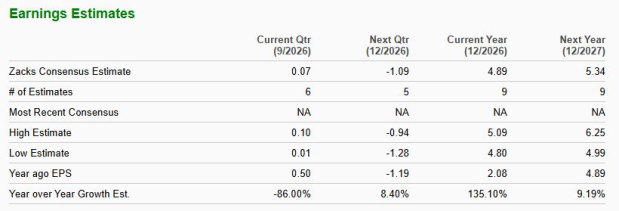
Image Source: Zacks Investment Research
CNC stock currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>This article originally published on Zacks Investment Research (zacks.com).
