AI Drives Storage Demand: Will It Boost Lam Research's NAND Growth?
Lam Research CorporationLRCX sees a major opportunity in NAND as AI workloads increase demand for high-capacity and fast-access storage. The company expects its served available market (SAM) per wafer in NAND to double from 128-layer technology to 500-plus-layer devices. This potential expansion could create a significant growth opportunity for Lam Research as memory makers move toward more complex architectures.
AI is an important factor behind this shift. Larger AI models and longer context windows require more persistent storage, increasing the need for high-density NAND. During its fourth-quarter fiscal 2026 earnings call, Lam Research revealed that customers are already increasing bit supply while converting existing equipment to 200-plus-layer NAND production. As layer counts rise, manufacturing becomes more difficult, requiring more advanced etch and deposition processes.
Lam Research is well-positioned to benefit from this rising equipment intensity. The company expects deposition and etch requirements to increase by roughly two times as semiconductor architectures become more three-dimensional. In NAND, LRCX has technologies such as Akara conductor etch and ALTUS deposition systems that address the challenges of deeper and more complex structures.
The near-term momentum is also encouraging. In the fourth quarter, Lam Research’s NAND revenues doubled sequentially, helping drive record overall results. The company’s total revenues increased 15% sequentially to a record $6.72 billion, while non-GAAP earnings per share jumped 24% to $1.82.
AI appears to be a key catalyst for NAND demand. If layer counts continue rising, Lam Research could capture greater equipment spending as its NAND SAM expands. The Zacks Consensus Estimate for fiscal 2027 is currently pegged at $34.41 billion, indicating 48.1% year-over-year growth.
LRCX’s Rivals Also Benefit From AI-Driven Memory Spending
Lam Research’s competitors, Applied Materials, Inc.AMAT and KLA CorporationKLAC, are also benefiting from increasing demand for chip-making tools as AI increases demand for high-capacity storage and advanced memory.
Though Applied Materials has a modest exposure in the NAND memory market, it is a key competitor to Lam Research in deposition and etch equipment used in DRAM and high-bandwidth memory (HBM) manufacturing. In the third quarter of fiscal 2026, AMAT’s DRAM revenues (including HBM packaging) rose 52% year over year.
Applied Materials’ newly introduced enhanced Centura Prime epitaxy and Producer Avila 2 PECVD improve DRAM performance and enable higher-layer-count HBM. During its last earnings call, the company expected a sizeable increase in DRAM revenues during the second half of 2026, indicating memory-related process spending to be the major tailwind for the company’s growth.
KLA offers process-control equipment that helps memory manufacturers detect defects and improve yields as NAND structures become more complex. KLA expects memory to represent about 27% of its semiconductor process-control systems revenues in the first quarter of fiscal 2027, with NAND accounting for roughly 10% of its memory business.
KLA expects the broader wafer equipment market to reach the low-$150 billion range in 2026, supported by AI, HBM and greater process complexity.
LRCX’s Share Price Performance, Valuation and Estimates
Lam Research shares have surged 103% year to date compared with the Zacks Electronics – Semiconductors industry’s 39.1% rise.
Lam Research YTD Price Return Performance
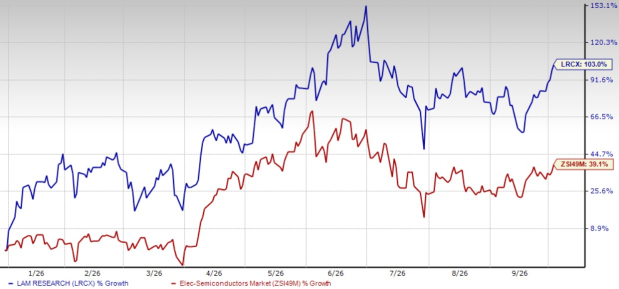
Image Source: Zacks Investment Research
From a valuation standpoint, Lam Research trades at a forward price-to-earnings ratio of 35.25, significantly higher than the industry’s average of 14.21.
Lam Research Forward 12-Month P/E Ratio
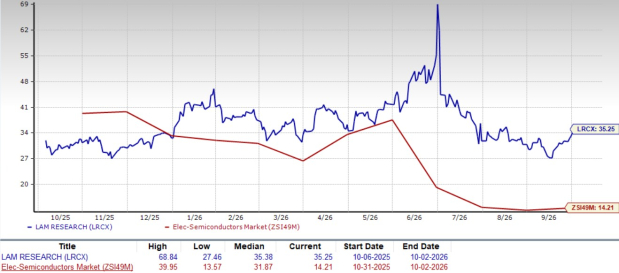
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Lam Research’s fiscal 2027 and 2028 earnings implies year-over-year increases of approximately 60.4% and 21.5%, respectively. Estimates for fiscal 2027 have been revised upward over the past 60 days, while fiscal 2028 estimates have been revised northward in the past 30 days.
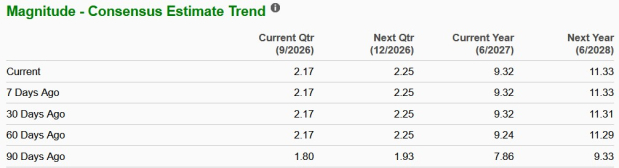
Image Source: Zacks Investment Research
Lam Research currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpThis article originally published on Zacks Investment Research (zacks.com).
